As parents, we spend years helping our children prepare for the future. We encourage them to study, choose the right subjects, develop skills and think carefully about their career choices. However, there is another important life skill that often receives far less attention: financial literacy.
A teenager may leave school knowing how to solve mathematical equations, write essays and prepare for examinations, yet still have very little understanding of how to manage money. They may not know how to create a budget, understand interest, differentiate between saving and investing or recognise the long-term consequences of poor financial decisions.
Financial literacy is not about teaching teenagers how to become wealthy overnight. It is about helping them develop a healthy and practical understanding of money before they begin making important financial decisions independently.
Why Financial Literacy Should Start Early
Many young adults begin learning about money only when they start earning it. Suddenly, they may have to manage a salary, pay bills, understand taxes, use credit cards and make decisions about saving or investing. Learning all of this at once can feel overwhelming.
Introducing basic financial concepts during the teenage years can make this transition easier. Teenagers do not need to understand complex financial markets or advanced investment strategies. They simply need a strong foundation.
The earlier they understand that money requires planning and decision-making, the better prepared they may be when they begin managing their own finances. Financial literacy can also help teenagers understand that earning money is only one part of financial wellbeing. How they manage, save and use that money matters too.
Start With the Difference Between Wants and Needs
One of the simplest and most valuable financial lessons parents can teach is the difference between wants and needs.
A need is something essential, while a want is something we would like to have but can live without. Of course, the difference is not always completely clear, and this can lead to useful discussions.
For example, a teenager may genuinely need a laptop for schoolwork, but they may want the most expensive model available. Helping them think about the difference between what is necessary and what is desirable can encourage more thoughtful spending decisions.
This does not mean parents should never buy their children things they want. The purpose is to help teenagers understand that every financial decision involves choices. Spending money on one thing may mean having less available for something else.
Learning this concept early can help young people become more conscious consumers.
Teach Them How to Budget
Budgeting may sound boring to teenagers, but it is one of the most practical skills they can learn.
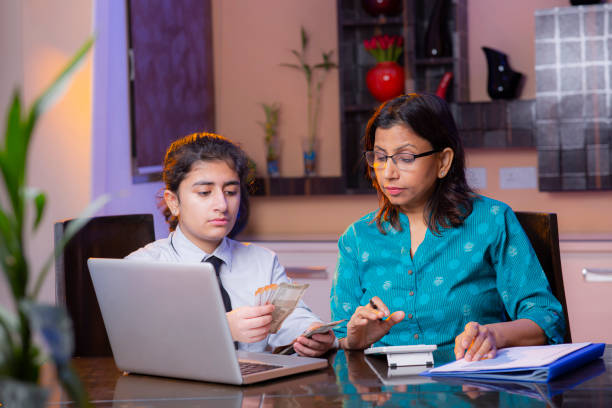
If your child receives pocket money, encourage them to think about how they use it. They can divide it into different categories, such as spending, saving and perhaps giving or contributing towards something meaningful.
The amount does not matter as much as the habit.
For example, instead of simply giving your teenager money whenever they need something, you can occasionally encourage them to plan how they will use the money they already have. If they want to save for something larger, help them calculate how long it may take.
This can teach patience, planning and the importance of making choices. It can also help them understand that a budget is not about preventing them from spending money. It is about helping them decide where their money should go.
Help Them Understand Saving
Saving is one of the first financial habits teenagers can develop.
Many young people see saving as something they will begin later, once they start earning a significant income. However, the habit of saving can begin with even a small amount of money.
If your teenager receives pocket money, a gift or earns money through an appropriate part-time activity, encourage them to set aside a portion before spending the rest.
The goal is not to force them to save every rupee. They should also learn that money can be used for enjoyment and experiences. The important lesson is balance.
Saving can also teach delayed gratification. If teenagers learn that they can wait and save for something they genuinely want, they may become less likely to make impulsive financial decisions in the future.
Introduce the Basic Idea of Investing
Once teenagers understand the importance of saving, parents can gradually introduce the basic idea of investing.
Saving generally involves keeping money aside for future use, while investing involves putting money into assets or opportunities with the expectation that it may grow over time, although investments can also involve risk.
Teenagers do not need to start making complicated investment decisions immediately. However, they can learn simple concepts such as the relationship between risk and return, the importance of long-term thinking and the power of compounding.
The most important lesson is that money can potentially grow over time, but financial decisions should not be based on rumours, social media trends or promises of quick returns.
Encourage your teenager to understand something before putting money into it. The habit of asking questions and learning before making a financial decision can be extremely valuable.
Talk Openly About Earning Money
Teenagers should understand where money comes from.
They do not need to know every detail of the family's financial situation, but it can be helpful for them to understand that money is connected to work, skills, effort and responsibility.
Talk about different ways people earn money. Discuss careers, businesses, freelancing and entrepreneurship. Help them understand that income can vary depending on skills, experience, demand and the value someone provides.
This can also be a useful opportunity to connect financial literacy with career planning. A teenager who understands the relationship between education, skills and earning opportunities may be better prepared to make thoughtful decisions about their future.
However, it is equally important to avoid teaching children that money is the only measure of career success. A meaningful career decision should consider interests, strengths, values, lifestyle and opportunities, not simply the highest possible salary.
Teach Them About Digital Money and Responsible Spending
Today's teenagers are growing up in a world where money is often invisible.
UPI payments, digital wallets, online shopping and subscriptions can make spending feel effortless. A teenager may click a button and make a purchase without experiencing the feeling of physically handing over cash.
This makes it even more important to teach awareness.
Help your child understand how digital payments work and encourage them to track their spending. Small purchases can quickly add up, especially when subscriptions and online shopping are involved.
Discuss the importance of protecting passwords, being cautious about suspicious links and never sharing sensitive financial information. Teenagers should also understand that online offers promising easy money or guaranteed returns can sometimes be misleading or fraudulent.
The goal is not to make them afraid of technology. It is to help them become responsible and careful users of it.
Let Them Make Small Financial Mistakes
Parents naturally want to prevent their children from making mistakes, especially when money is involved. However, small and manageable financial mistakes can become valuable lessons.
If your teenager spends all their pocket money on something impulsively and later regrets not having enough for something else, that experience can teach an important lesson about planning.
You do not always need to immediately replace the money or rescue them from the consequences. Instead, talk about what happened and what they might do differently next time.
Of course, teenagers should be protected from serious financial risks. The idea is simply to allow them to learn from age-appropriate decisions while the consequences are still relatively small.
These experiences can help them develop judgement and responsibility.
Avoid Making Money a Taboo Topic
In many families, money is rarely discussed openly. Children may grow up understanding that money is important without ever learning how financial decisions are actually made.
Parents can change this by having age-appropriate conversations about everyday financial decisions.
For example, you can explain why you compare prices before making a purchase, why you choose to save for certain goals or how you decide whether something is worth spending money on.
You do not need to share private financial details. The purpose is simply to allow your teenager to see how responsible financial decisions are made.
These conversations can make financial topics feel less intimidating and help teenagers become more comfortable asking questions.
Final Thoughts
Financial literacy is not a single lesson that can be taught in one conversation. It develops gradually through observation, discussion and experience. The goal is not to turn your teenager into a financial expert before they leave school. It is to ensure that they have enough knowledge and confidence to make thoughtful decisions when they begin managing money independently.
Start with simple conversations about spending, saving and budgeting. Help them understand the difference between wants and needs. Introduce the basic idea of investing and explain why quick-money promises should always be approached with caution. Give them opportunities to make small financial decisions and, occasionally, learn from their mistakes.
The financial habits your child develops as a teenager may stay with them for years. Just as we prepare young people for careers and higher education, we should also prepare them for the everyday responsibility of managing money.
After all, financial independence is not simply about earning an income. It is also about understanding how to make wise decisions with what you earn.